Avoid 7 Year Credit Damage: Cosigner Car Loans for Clearwater Buyers
A cosigner can get you approved or land you a better rate when your credit is thin, but they become fully liable for the loan the moment you miss a payment. If you're a first-time buyer or working through credit challenges, a cosigner car loan can open doors a solo application cannot. Before you ask someone to sign on, check whether you can qualify on your own first.
TL;DR:
- A cosigner’s credit and income can improve approval odds and lower interest rates, but they become fully liable if the primary borrower misses payments.
- Cosigners are legally responsible for repayment without owning the vehicle, and missed payments can negatively impact both credit reports for up to seven years.
- Lenders generally require a cosigner with a credit score of around 670 or higher, a debt-to-income ratio below 50%, and steady, verifiable income.
- Removing a cosigner typically requires paying off the loan early, refinancing into the borrower's name, or requesting a formal cosigner release after consistent on-time payments.
- Using a cosigner works best when there is a trusted relationship, the borrower can afford payments, and both parties understand the financial responsibilities involved.
Table of Contents
- 1. What is a cosigner and how does it differ from a co-borrower
- 2. Benefits and risks of using a cosigner
- 3. What lenders typically require from a cosigner
- 4. How to apply with a cosigner: a step-by-step checklist
- 5. Removing a cosigner and safer alternatives
- 6. Why trust this guidance: dealer experience and buyer safeguards
- 7. Our take: when a cosigner makes sense and when it doesn't
- How Clearwater Largo Automotive helps with financing and paperwork
- Sources
- FAQ
1. What is a cosigner and how does it differ from a co-borrower
A cosigner is someone who adds their credit and income to your loan application without taking any ownership stake in the vehicle. A co-borrower, by contrast, shares both the debt and the title, meaning they have equal rights to the car and equal responsibility for the payments.
That distinction matters more than most buyers realize. Here's how the two roles break down:
- Cosigner: Legally responsible for repayment, but their name never appears on the title.
- Co-borrower: Shares ownership of the vehicle and equal responsibility for the loan.
- Credit reporting: Both roles show up on each person's credit report, and both are affected by missed payments.
- Lender rights: A lender can pursue a cosigner for the full balance without going after the primary borrower first.
We cover this split in more detail in our guide to joint auto loan requirements, including what it means for insurance and taxes.
2. Benefits and risks of using a cosigner
A cosigner can change the outcome of your loan application in a few concrete ways, but the tradeoffs are real and worth spelling out.
- Easier approval: Lenders weigh both applicants' credit and income, so a strong cosigner can offset a thin file.
- Potentially lower APR: Adding a qualified cosigner may improve your interest rate because lenders see less risk.
- Access to a newer or more reliable car: Better approval odds sometimes mean qualifying for a larger loan amount, enabling access to newer or more reliable vehicles.
- Legal liability for the cosigner: They owe the full balance if you stop paying, no exceptions.
- Credit damage for both parties: Missed payments can appear as derogatory marks on both credit reports for up to seven years.
- Higher debt-to-income ratio for the cosigner: The loan counts against them even if they never make a payment.
- Deficiency exposure after repossession: If the car is repossessed and resold for less than the balance, both borrower and cosigner can be pursued for the difference — a risk explained further in Who pays more than CarMax? Cash Buyers Vs. Dealer Trade-Ins.
- Relationship risk: Money problems between family or friends rarely stay contained to the loan itself.
Experian notes that lenders evaluate both applicants' credit history and DTI when setting APRs, which is why a cosigner's financial picture can shift your rate in either direction, not just yours.
Pro Tip: Set up automatic payments the day the loan funds, and ask the lender to give your cosigner account access or monthly statements so nothing slips through unnoticed.
3. What lenders typically require from a cosigner
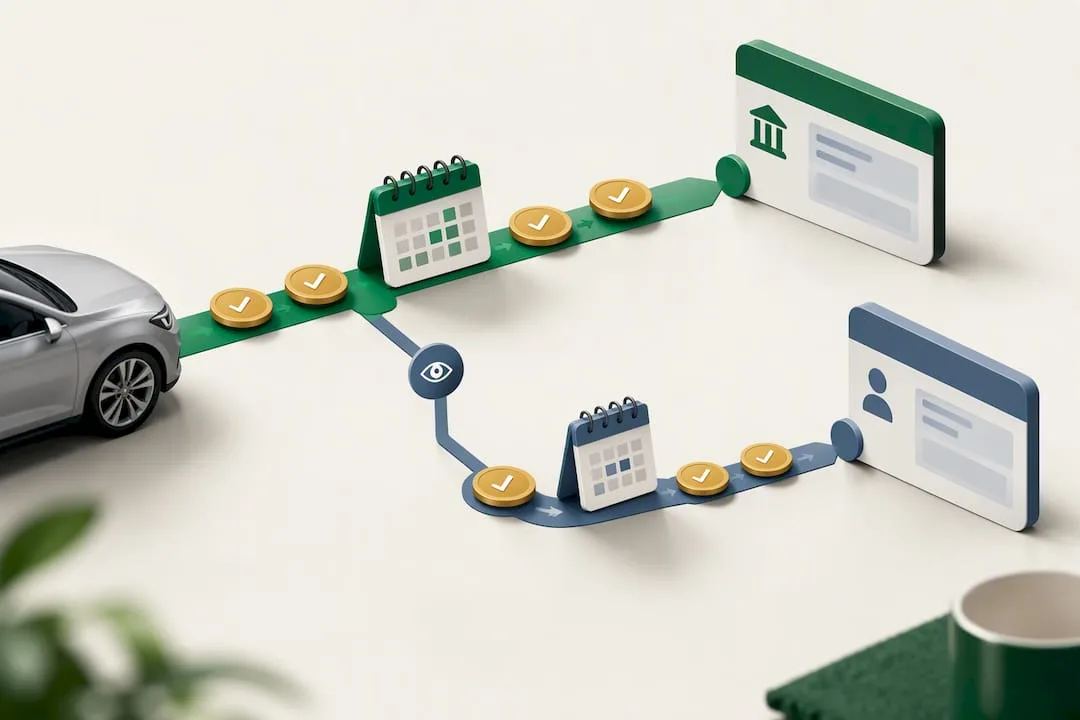
Lenders don't take just anyone. Most look for a cosigner who strengthens the application rather than one who barely qualifies themselves.
- Credit score: Lenders often look for a cosigner with a score around 670 or higher.
- Debt-to-income ratio: A DTI below 50% is a common threshold lenders check.
- Steady, verifiable income: Pay stubs or tax returns that show consistent earnings.
- Documentation: Government-issued ID, proof of address, and recent income records.
Before you finalize anything, ask the lender directly whether the primary borrower would qualify alone, and shop more than one lender to compare terms. Our post on proof of income for a car loan walks through exactly what documents lenders accept, and our breakdown of approval factors for 2026 covers the score and DTI thresholds in more depth.
4. How to apply with a cosigner: a step-by-step checklist
Applying with a cosigner takes a little more coordination than a solo application, but the process follows a predictable order.
- Pull both credit reports first so there are no surprises during underwriting.
- Calculate what you can actually afford, not just what you might be approved for.
- Shop multiple lenders and get prequalified before you commit to one offer.
- Gather documentation from both parties, including ID, income proof, and address verification.
- Expect two credit checks, since lenders evaluate combined risk across both applicants.
- Read the contract closely once approved, especially the sections on late fees and default.
- Set up auto-pay and keep communication open between borrower and cosigner from day one.
Our car payment calculator is a quick way to test affordability before you sit down with a lender.
Pro Tip: Bring both sets of documents to the same appointment if possible. It speeds up underwriting and avoids the back-and-forth that stalls approvals.
5. Removing a cosigner and safer alternatives
A cosigner isn't meant to be permanent, but getting them off the loan takes planning.
- Pay off the loan early: The simplest way to end the cosigner's liability entirely.
- Refinance into the borrower's name only: Requires the borrower to qualify solo at that point.
- Request a formal cosigner release: Some lenders offer this only after 12 to 24 months of on-time payments, and not every lender offers it at all.
If you'd rather avoid the cosigner route altogether, a few alternatives are worth considering: a co-borrower arrangement with shared title, a larger down payment to reduce the loan amount, or simply spending a few months building credit before you apply.
6. Why trust this guidance: dealer experience and buyer safeguards
Our team has experience helping buyers navigate financing decisions. That experience shapes how we talk about cosigners and risk.
- Transparent pricing: Every vehicle we list shows its price upfront, with no hidden fees added later.
- Thorough inspections: Cars are inspected and come with history reports before they're ever listed.
- Personalized assistance: Every inquiry is handled by a real person, not a call center script.
- Vehicle sourcing: If you're looking for a specific make or model, we can find it rather than pushing you toward whatever is on the lot.
Those practices matter whether you're financing solo or with a cosigner, because clear terms upfront reduce the chances of a costly surprise later.
7. Our take: when a cosigner makes sense and when it doesn't
We generally support a cosigner arrangement when there's a trusted relationship, the borrower can genuinely afford the payments, and both sides have talked through a repayment plan in plain terms. We advise against it when the cosigner is stretching their own budget to help, when the borrower isn't ready for the responsibility, or when a cosigner is being used as a short-term patch instead of addressing the credit issue underneath. If you want to talk through your specific situation, reach out. We're happy to walk through financing options with you directly.
— CL Auto
How Clearwater Largo Automotive helps with financing and paperwork
Getting a cosigner car loan right often comes down to having someone walk you through the paperwork instead of leaving you to decode it alone. That's where our financing help makes a real difference for Clearwater and Largo buyers.
- In-house lender relationships: We work with multiple lenders so you can compare offers rather than settle for the first one.
- Documentation support: We help both borrower and cosigner assemble what lenders actually ask for.
- Transparent pricing: Every car on our lot is priced upfront, so financing decisions aren't complicated by hidden fees.
Visit our financing page to start the conversation, or use our payment calculator to see what fits your budget before you apply. If you're not seeing the right car on our lot, our vehicle sourcing service can help you find it without stretching your loan further than it needs to go.
Sources
For more detail, the CFPB's cosigner guidance, Experian's credit-impact research, and Bankrate's cosigner-release breakdown cover the legal and credit details in full.
- How cosigning affects credit | Experian
- How to remove a co-signer from a car loan | Bankrate
- Should you get a cosigner on a car loan? | Experian
FAQ
Is it a good idea to cosign a car loan?
It depends on whether you can comfortably absorb the payments if the primary borrower can't. Cosigning means you're legally on the hook for the full balance, so it only makes sense with a borrower you trust and a plan you've both discussed in detail.
Can I legally take a car I cosigned for?
No. A cosigner has no ownership claim on the vehicle, since only the borrower's name appears on the title. If the borrower defaults, the lender can repossess the car, but the cosigner still owes any remaining balance and has no legal right to the vehicle itself.
What is required for a cosigner on a car?
Lenders typically want a credit score around 670 or higher and a debt-to-income ratio below 50%, along with proof of steady income. Expect to provide ID, pay stubs or tax returns, and proof of address during the application.
What disqualifies a cosigner?
A low credit score, unstable or unverifiable income, and a debt-to-income ratio above what the lender allows are the most common disqualifiers. Lenders also tend to reject cosigners who already carry heavy existing debt, since it raises the risk that they couldn't absorb the loan if needed.